
Hippo Staff Writer · Published 11 January 2022 · 4 min read
Vaping vs smoking: How it affects your Life Insurance
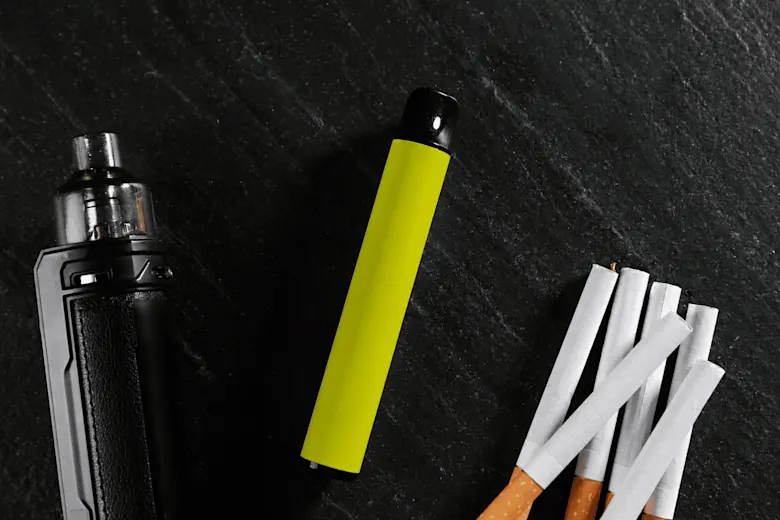
Is vaping bad for you? Or is it different to smoking cigarettes, cigars or pipes? And how does it affect your Life Insurance premium?
Vaping – that's the 'smoking' of electronic cigarettes – has been marketed as a safer alternative to smoking, with many cigarette smokers making the switch for perceived health benefits. While the aerosol emitted by e-cigarettes doesn't contain all the contaminants of tobacco smoke, it does still deliver highly addictive nicotine, cancer-causing chemicals, volatile organic compounds and heavy metals like nickel, tin and lead.
It's for these reasons that insurers assess people who vape in the same way as those who smoke cigarettes, and charge them the same insurance rates.
Arthur Zerf, Head of iWYZE Life at Old Mutual iWYZE, says that there's currently no evidence, based on medical studies, to support applying different terms depending on the device, frequency or substance used.
"The Old Mutual iWYZE definition of a smoker includes smoking tobacco, nicotine or any nicotine substitution products," he says. "This means not only cigarette, pipe or cigar smoking, but also the consumption of any products containing nicotine such as patches, chewing gum, vaping, snuff or other organic substances. Customers who vape are charged the same as customers who use any other tobacco, nicotine or any nicotine substitution products."
What is Vaping?
Vaping is a generic term used to describe the use of electronic cigarettes. The difference between vaping and traditional cigarette smoking is that vaping produces a heated vapour steam containing chemical aromatic or non-aromatic flavours and nicotine with no combustion; while smoking generates smoke due to the incomplete combustion of tobacco.
"In both cases, smoke is inhaled by the smoker," says Zerf. "The prognosis of vaping is similar to smoking traditional tobacco, nicotine or nicotine substitution products. The important causes of mortality and morbidity associated with vaping consumption are cancer, cardiovascular disease and chronic respiratory disorders."
In South Africa, e-cigarettes don't fall under the current Tobacco Products Control Act. Instead, they technically fall under the Medicines and Related Substances Act of 1965. But while, legally speaking, they should be registered with the South African Health Products Regulatory Authority (SAHPRA) and sold by prescription only, they're widely available as consumer products, even sold at kiosks in shopping centres.
The Control of Tobacco Products and Electronic Delivery Systems Bill is supposed to regulate smoking in general – including vaping – but has yet to be passed into law, despite being closed for public comment since 2018.
Vaping vs Smoking Cost
Zerf says that people should be aware of the consequences of smoking, regardless of the product they use. "Long-term vaping may result in developing similar complications as smoking tobacco or similar products. Smoking in any form is harmful and should be avoided," he says.
"Non-smokers enjoy cheaper premiums. If the customer was issued a Life Insurance policy with smoker rates, there is an opportunity to review their premiums six months after giving up smoking, provided that they produce a negative cotinine test." (Cotinine, the main breakdown product from nicotine, can be detected in the body for up to three months after ingestion. Hence the six-month wait.)
Aside from the harmful chemicals ingested by vapers, the American Heart Association warns that the increasing popularity of vaping may 're-normalise' cigarette smoking, which has declined for years. They say that reversing the hard-won gains in the global effort to curb smoking would be catastrophic.
Smoking is still the leading preventable cause of death and is responsible for the loss of 480 000 lives in America, each year. In South Africa, that number is around 44 000 under 'normal' circumstances, and likely much higher during Covid-19 because of the damage smokers cause to their lungs.
Dangers of Vaping
When it comes to claims for illness, insurers have the right to ensure that your declarations on initiating – and continuing – your policy, have been adhered to.
"At claim stage, we are guided by the medical evidence provided for the claimable condition," says Zerf. "If the evidence indicates that the client has a history of smoking and was a smoker at application stage, we reserve the right to review the original underwriting terms and possibly reconstruct the policy from inception with the correct rates keeping the premium constant."
The approach at the claims stage would be similar to the underwriting approach at the new business stage, he says. "In a nutshell, smoker rates would be applied from inception."
Compare Life Insurance quotes with Hippo's easy comparison tool – and don't forget to be honest about your pre-existing conditions or behaviours to ensure that you're covered when you need it most!
This article is for informational purposes only and does not constitute financial, legal, medical or insurance advice. Hippo is a comparison site helping you evaluate quotes from trusted South African insurers. Always review policy details before making changes. Quotes are risk profile dependent and subject to annual review. No fees are charged for using Hippo’s comparison service. HAS (Pty) Ltd and HCS (Pty) Ltd are authorized FSPs. Terms and conditions apply.
Related Articles
2026-09-23
How to apply for Medical Aid in South Africa
Choosing the right Medical Aid can feel like a lot to take in, but the process itself is straightforward once you know what's expected. This guide walks through who qualifies, what documents you'll need and why you should consider comparing Medical Aid plans before you commit to one
Read More
2026-09-22
Latest Medical Aid Premium Increases: What You Need to Know
If you’re planning your 2027 budget, brace yourself before opening your medical aid statement. Major schemes are preparing to announce their increases for the year, and while the percentages differ slightly, one thing’s certain: healthcare is getting more expensive—again.
Read More
2026-09-14
Comparing two of South Africa’s leading Medical Aid rewards programmes
Medical aid rewards programmes like Discovery Vitality and Momentum Multiply help South Africans live healthier lives while offering perks like discounts and cashback. This blog compares these two popular programmes to help you understand their benefits and how they work.
Read More
2026-09-08
What you need to know when switching Medical Aids
Many people don't realise it but it's important to reassess your medical aid scheme every year. Schemes themselves will revise their benefits annually, so members should do the same to understand whether they're receiving the optimum value based on their individual needs.
Read More

Hippo Comparative Services (Pty) Ltd is an authorised financial service provider.
FSP number: 16357. Block A, Steyn City Capital Park, Erling Road, Riverglen, Dainfern, 2191
*Based on independent research by Kaufman Levin & Associates 2025.


© Copyright 2026 Hippo Comparative Services (Pty) Ltd. All Rights Reserved.