
Hippo Staff Writer · Published 22 July 2021 · Updated 20 August 2026 · 7 min read
Claiming from Insurance? Don’t wait too long…
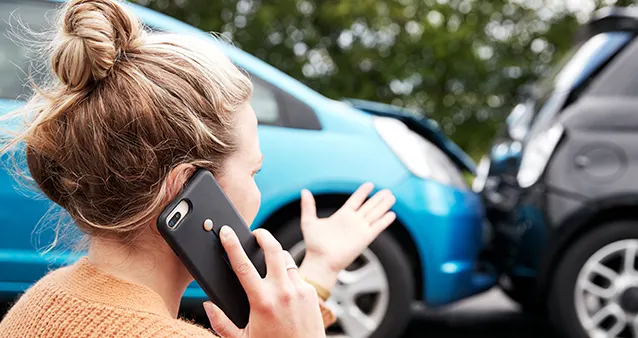
You've paid your premiums faithfully for years. Then you need to claim, and discover - too late, of course - that a deadline slipped, a document went missing or the very thing that happened to you was never covered in the first place.
Most rejected insurance claims are avoidable, Hippo unpacks the typical claims process below.
Car Insurance Claims
First things first: report the incident, then start the claims process
When something happens, such as a car accident, break-in, criminal act or other insured event, there are usually two clocks that start running..
The first is the police or accident report, which may require a visit to a police station. For a car accident, theft, or any incident involving a crime, you typically need to report it to the South African Police Service within 24 hours, or on the first working day if no one was hurt. You’ll need the case number, your policy number and other insurance information when you submit your claim.
If you are involved in a car accident, contact emergency services if anyone is hurt, then exchange information with the other party and record the contact details of all parties involved. Where possible, note the number plate and details of the vehicles involved, take photographs of the accident scene, and collect contact details for any witnesses. Even if you feel shaken, make a note of the date, road signs, weather, other driver’s details and any available witness statements.
The second is the claim itself. Most insurers give you a set window to lodge a claim from the date of the incident. It’s often around 30 days, though it varies by policy. Some are stricter, some more lenient, and the only way to know yours is to check your policy schedule. The safest move is the simplest: report as soon as you reasonably can. "I was busy" is not a defense an insurer is obliged to accept.
A useful way to think about it is the sooner you report, the fresher the evidence, the cleaner the paperwork, and the fewer openings there are for a claim to be questioned.
Required documents to keep on hand for a Car Insurance claim
The claims process goes more smoothly when you can produce evidence and required documents quickly. The time to gather this is before anything goes wrong, not while you're standing in the rain next to a dented bumper. Keep these documents somewhere accessible, and ideally backed up digitally:
Your insurance policy, policy schedule and policy number. The one that lists what's covered, your excess, and your obligations. Most people have never read theirs. Be the exception.
Your ID, ID number and proof of residence. Standard for verifying who you are.
Proof of ownership for insured items. Receipts, invoices, or valuation certificates for anything valuable, especially jewellery, electronics, and "all-risk" items you carry around. No proof of ownership is one of the most common reasons a contents claim stalls.
Photographs. Of high-value possessions while they're intact, and of any damage when it happens. Date-stamped where possible.
A police case number and accident report, where the incident involves a car accident, theft or criminal act (this applies to criminal acts involving Home and Business Insurance claims too).
Records of communication with your insurer, insurance agent or insurance company, including names, dates, reference numbers and contact details. If a dispute ever arises, this is gold.
Keep this information ready before you need to complete a claim form or respond to a request from your insurer.
For cars specifically, keep your driver’s licence, vehicle registration, insurance information and a record of the accident details, including the other party's information, photos of the scene, and any witness contacts.
Common exclusions for different insurance products
Every insurance policy has exclusions, which may depend on the circumstances of the event, the insured person and other factors. They're not hidden, exactly; they're in your policy document somewhere. Exclusions exist to keep cover affordable and to encourage sensible behaviour, but they're also where good-faith claimants get blindsided.
Here are the common exclusions by product:
Car Insurance
For a Car Insurance claim, your insurer may assess the vehicle’s condition, the driver’s conduct, fault and the details of the accident.
Exclusion | Reason |
Driving under the influence | Accidents that happen while you're over the limit (0.05g per 100ml, or 0.02g for professional drivers) are almost universally excluded, and so are any resulting injury or liability claims. |
An unroadworthy vehicle | Worn tyres, faulty brakes, or an expired licence disc can void a claim, even if they didn't cause the incident. |
Non-disclosure | Getting the regular driver wrong, understating mileage, or leaving out a modification can render your cover invalid, sometimes from the very start. |
Home Insurance
Often, an asset register tracking everything in your home, accompanied by an evaluation comes in handy for Home Insurance claims. Home cover may also have limits for losses caused by gradual damage, negligence, a criminal act or certain natural disasters.
Exclusion | Reason |
Negligence | Leaving doors unlocked, windows open, or valuables unattended in public can sink a theft claim. |
Gradual damage | Damp, mould, pest damage, and slow deterioration usually aren't covered, since these are seen as maintenance issues. |
Unspecified high-value items | Expensive watches, jewellery, and collectables often need to be listed and separately insured rather than lumped under general contents. |
Items away from home | Possessions lost or stolen outside the house typically need all-risk cover, not just standard home contents cover. |
Life and Disability Cover
A death certificate is among the essential documents required when a Life Insurance claim follows a death. Life Insurance claims may require additional information and documents, depending on the cause of death, medical history and policy terms.
Exclusion | Reason |
Material non-disclosure | Not declaring a pre-existing condition or a relevant habit (smoking is the classic) at application is the leading reason these claims are declined. |
Waiting periods and suicide clauses | Many policies impose an initial period during which certain claims, including suicide, aren't paid. |
Excluded or high-risk activities. | Some policies exclude hazardous pursuits (like spelunking or skydiving) unless you've declared and covered them. |
Business Insurance
Similarly to Home Insurance, there may also be limits for losses caused by gradual damage, negligence, a criminal act or certain natural disasters.
Exclusion | Reason |
Underinsurance | Insure your stock or equipment for less than its true value and the "average" clause can reduce your payout proportionally, even on a partial loss. |
Specific perils | Events like riots, civil unrest, and terrorism are generally excluded from standard cover and sit instead with SASRIA, the state-backed special-risks insurer, which you pay for as an add-on. |
Professional and liability gaps | A general business policy may not cover a client's claim that your advice caused them loss, or a public liability incident. Those are often separate covers. |
None of this means insurers are looking for reasons to say no. In fact, South African law places the burden on the insurer to prove that an exclusion applies, and to point to the exact policy wording it's relying on. But the cleanest way to win that argument is never to have it - by knowing your exclusions upfront.
If your insurance company rejects your claim
A rejection isn't necessarily the end of the road, but the clock - yes, another one - starts ticking immediately.
Start with your insurer’s internal dispute process and submit your request, evidence and required documents in writing. Under the Policyholder Protection Rules, if you hold a personal (non-commercial) policy, you have 90 days from the rejection to make formal representations to your insurer challenging the decision. Use them. Put your case in writing, complete any required claim form or dispute form, attach the evidence and keep copies of everything you file.
If that does not resolve the matter, contact the National Financial Ombud Scheme using its published contact details. This is the part that's changed since you may have last looked: the old Ombudsman for Short-Term Insurance (OSTI) no longer exists as a standalone office. As of 1 March 2024, it merged with three other ombud schemes into the single National Financial Ombud Scheme. Short-term insurance disputes (car, home, business) are now handled by the NFO's Non-Life Insurance Division. The service is free, and you can reach it at nfosa.co.za or 0860 800 900.
Most insurance policies contain a time-bar clause: a contractual deadline (commonly six months after the rejection) by which you must take legal action, separate from the broader three-year prescription period set by the Prescription Act. Miss it and you can lose the right to enforce an otherwise valid claim. The good news is that lodging a complaint with the NFO before that deadline suspends the time-bar clock while your case is considered, which is exactly why you shouldn't sit on a rejection hoping it resolves itself.
The lesson that ties the whole thing together
Insurance rewards the prepared and punishes the slow. Report quickly, keep your paperwork in order, know your exclusions, and act fast if something goes wrong.
If you're not confident your current cover fits your life, or you suspect you're paying for the wrong things, then it's worth comparing. Hippo lets you compare multiple insurance quotes side by side, so you can see what you're covered for before you ever need to claim.
This article is for informational purposes only and does not constitute financial, legal, medical or insurance advice. Hippo is a comparison site helping you evaluate quotes from trusted South African insurers. Always review policy details before making changes. Quotes are risk profile dependent and subject to annual review. No fees are charged for using Hippo’s comparison service. HAS (Pty) Ltd and HCS (Pty) Ltd are authorised FSPs. Terms and conditions apply.
Related Articles
2026-09-18
What is Cyber Extortion Cover in South Africa?
In this guide, we'll unpack what Cyber Extortion means, how it fits into the wider world of Business Insurance in South Africa.
Read More
2026-09-03
The basics of Motorcycle Insurance
With motorbikes being more fuel-efficient than cars, and scooters being the vehicle of choice for food delivery, we're seeing more and more bikes on the road these days. If you're considering joining the two-wheel brigade, here's what you need to know from an insurance point of view.
Read More
2026-08-24
6 reasons to consider Pet Insurance in South Africa
Pet Insurance helps cover the cost of veterinary treatment when a dog, cat or other pet gets sick or injured. Plans generally include accident cover and illness cover, and some extend to routine care such as vaccinations and check-ups. Pet Insurance is a short-term insurance product instead, which means insurers can tailor plans and premiums to the individual pet, rather than charging every policyholder the same rate.
Read More
2026-08-20
What Business Insurance cover does your business need?
Business Insurance exists to absorb those shocks, so a single bad day does not close your doors. The catch is that it is not one product. It is a set of covers you mix and match to fit what your company does, owns and risks. This guide walks through the main types of Business Insurance, who needs each, and how to size your cover without overpaying.
Read More

Hippo Comparative Services (Pty) Ltd is an authorised financial service provider.
FSP number: 16357. Block A, Steyn City Capital Park, Erling Road, Riverglen, Dainfern, 2191
*Based on independent research by Kaufman Levin & Associates 2025.


© Copyright 2026 Hippo Comparative Services (Pty) Ltd. All Rights Reserved.